Welcome to the Blooming Mindset. I’m Ruth Rieckehoff, and I’m so glad you’re here. Some of my emails include affiliate links. If you choose to purchase, I may earn a small commission, at no extra cost to you. I only share what I’ve personally used, trusted, and found meaningful enough to pass along.
Beloved Architect of Identity,
What if doing everything yourself isn’t as financially responsible as you think?
I was reading an article about how modern conveniences have made us impatient.
One example caught my attention.
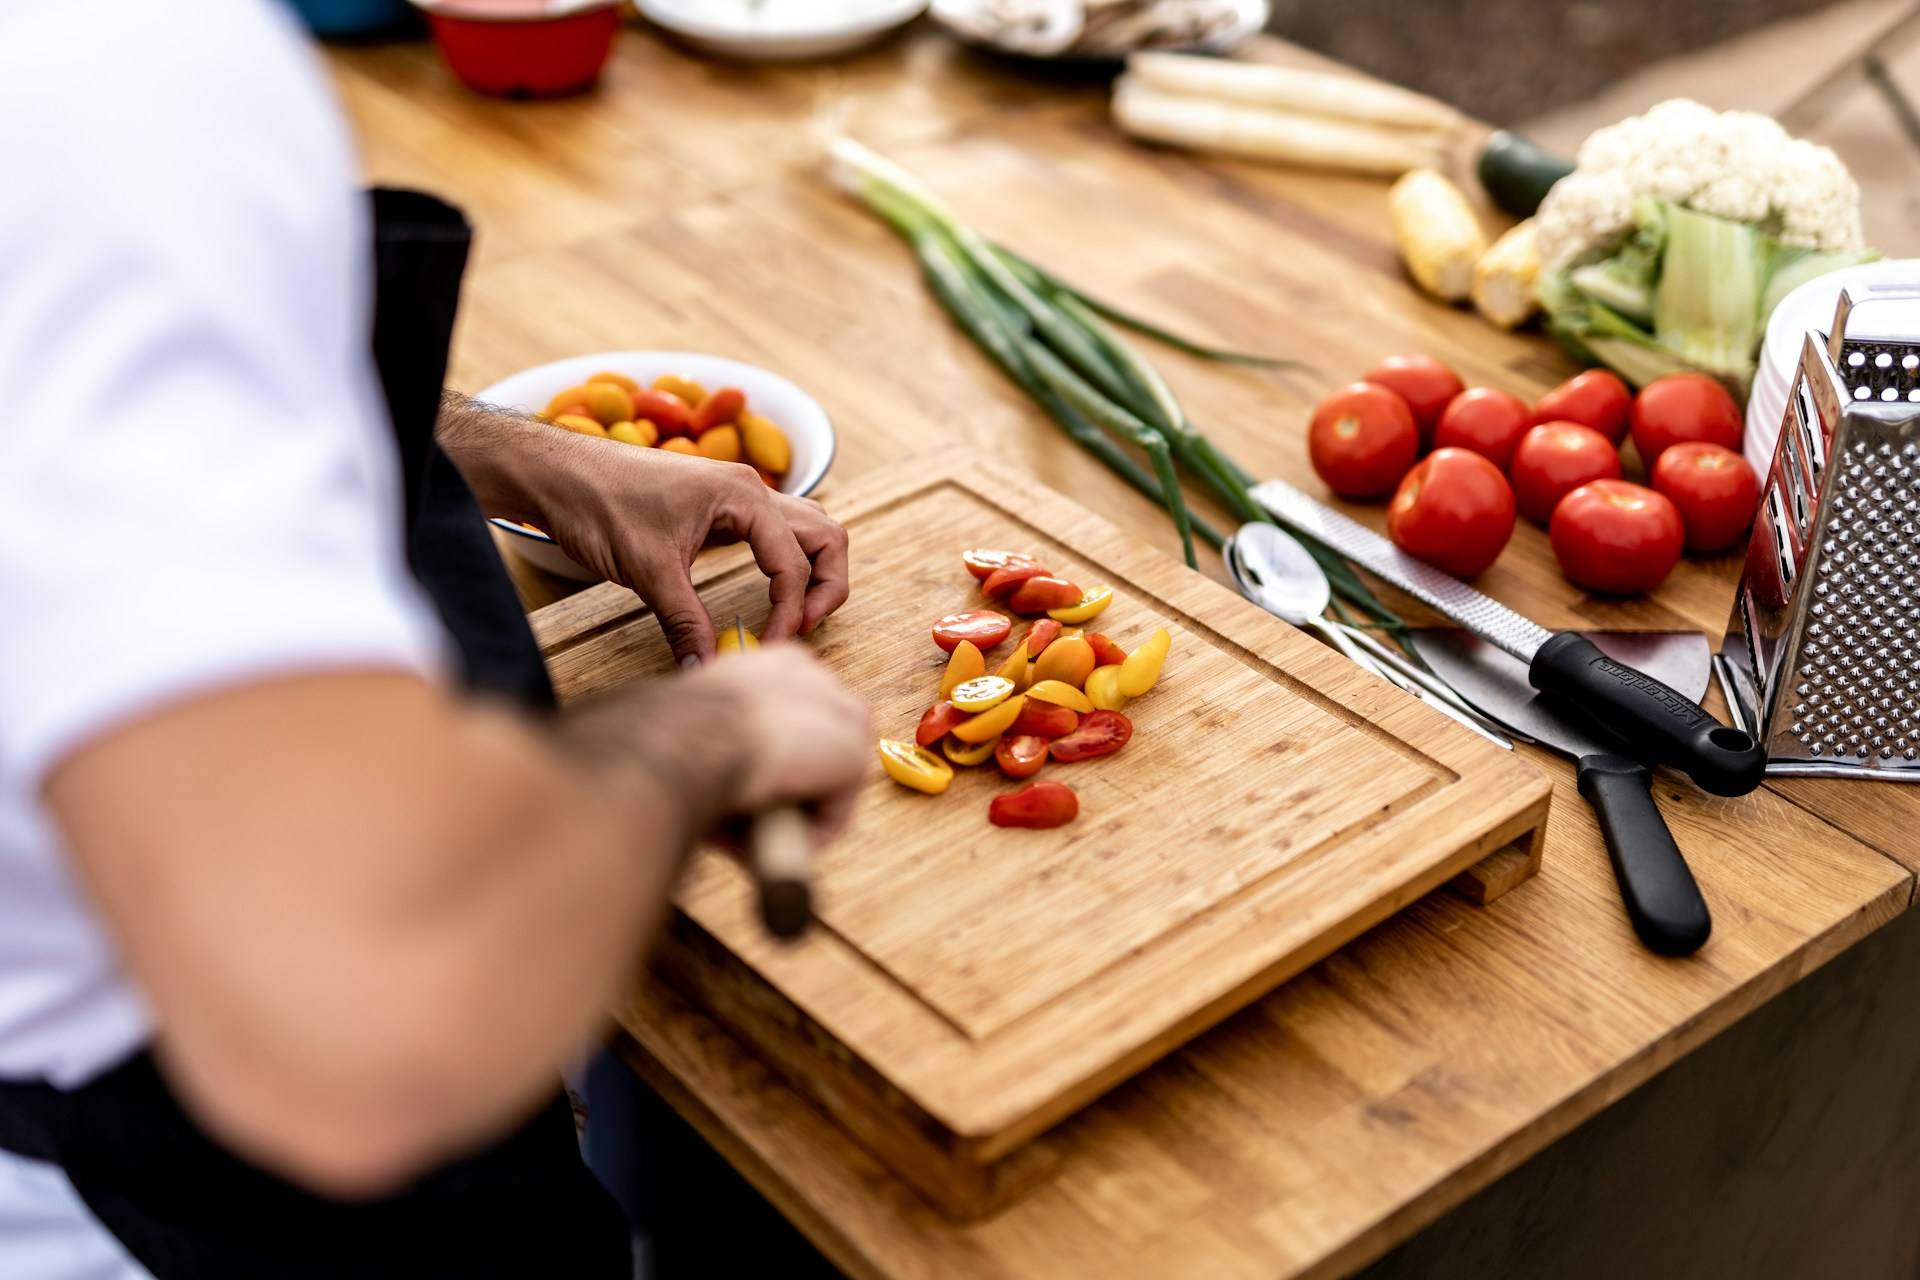
The author argued that people no longer want to spend an hour cooking a nourishing meal. Instead, they rely on prepared food, delivery services, and appliances that make cooking easier.
And somehow, this was presented as a problem.
I found myself wondering: Why?
What if someone doesn’t enjoy cooking?
What if they can purchase a nutritious meal and spend that hour exercising, reading, spending time with family, or simply resting?
Why should preparing the meal themselves be considered the better choice?
I think we sometimes confuse the ability to tolerate difficulty with the obligation to tolerate it.
And this mindset can quietly influence how we manage money.
We’re often told that building wealth requires sacrifice.
Cancel the subscriptions. Cook every meal. Clean your own house. Stop paying for things you can do yourself.
There’s wisdom in questioning unnecessary expenses.
But there’s also a point where saving money becomes the objective rather than a means to something greater.
Think about it.
We have washing machines because washing clothes by hand consumes valuable time.
We automate investments because we don’t need to spend hours managing repetitive transactions.
Yet we sometimes romanticize doing things the hard way, even when better alternatives exist.
Of course, there’s another extreme.
Paying for every convenience without questioning its value.
A subscription here. A delivery fee there. Another service to eliminate a minor inconvenience.
Before long, your lifestyle becomes considerably more expensive without necessarily becoming better.
Neither extreme is particularly wise.
A better approach is selective convenience.
Spend money when it meaningfully improves your life and fits your financial priorities.
Save money when the convenience offers little value.
And do things yourself when you enjoy them, want to develop a skill, or value the independence they provide.
After all, wealth isn’t simply about accumulating more money.
It’s also about expanding your ability to choose how you spend your time, energy, and attention.
The goal isn’t to make everything easier. It’s to stop making life unnecessarily difficult.
Until next time, keep blooming,
Ruth
Reflect
- What activity do you continue doing yourself primarily to save money, even though you dislike it?
- What convenience do you regularly purchase that adds little to your quality of life?
Reframe
Instead of asking: Can I do this myself and save money?
Try asking: Is doing this myself the best use of my time, energy, and resources?
Saving money is valuable. But so are the hours of your life.
Actionable Transformation
- Identify your high-value conveniences. Choose two or three services, tools, or devices that genuinely improve your life. Keep them without unnecessary guilt, provided they fit your financial plan.
- Question automatic spending. Review recurring convenience expenses. Would you purchase them again today, knowing how much value they actually provide?
- Experiment before committing. Try outsourcing one activity you dislike. Notice what you do with the recovered time and whether the benefit justifies the cost.
P.S. I wonder how many people would happily pay someone to fold their laundry but wouldn’t give up making their morning coffee for anything. That’s the beauty of personal preferences. We don’t all need to simplify the same things.
Join the conversation: Follow me on X.